• Home
  • Free Funding Guide
  • What We Offer
    • Products
    • Services
    • Free Guide
  • About Us
  • Contact
  • Sign Up

  • Ask Joe Any Question!
  • Business Credit Cards
  • Business Line of Credit
  • Topics

3 Best Credit Unions for Small Business Banking in 2025

By Joe

Best Credit Union for Small Business 2020

Key Takeaways

  • Credit unions often offer lower fees, better interest rates, and flexible lending terms.
  • They provide personalized service and easier access to business credit.
  • Navy Federal, Financial Resources, and Sound Credit Union are our top choices.
  • Other options include Alliant, Consumers, America First, and Digital Federal.
  • Small community banks can also offer lower fees and flexible terms.
  • Research and compare options to find the best fit for your business.

As a small business owner or founder, where you choose to do your banking can have a major impact on your long-term operations. And, when researching the best bank or credit union for small businesses, you may have realized that you would rather work with a credit union. Now, let’s look at the top credit unions for small business banking. 

What you’ll find here: 

  • Are Credit Unions Better Thank Banks?
    • Are Credit Unions Better for Business Accounts?
  • The Best Credit Unions for Small Business
    • 1. Navy Federal Credit Union
    • 2. Financial Resources Credit Union
    • 3. Sound Credit Union
    • +Honorable Mentions
  • Final Thoughts

So, let’s get to it. 

First, Are Credit Unions Better Than Banks? 

There’s a longstanding debate about whether banks or credit unions are “better.” And, it’s important to understand the difference to answer this question. A bank is a for-profit institution and a credit union is a nonprofit organization that provides comparable financial services. So, what are the advantages of credit unions? 

At most credit unions, the shareholders are the members while banks funnel their profits to up the chain to its owners. This means that there is more opportunity for members to save on services and earn a larger percentage of total interest accrued with savings accounts and other investments. 

As a credit union member, you typically end up with lower interest rates and fees (a major plus). On the flip side, major banks typically have more branch locations where customers can do business and invest more in apps and convenience services. So, you could say that which is the best is a matter of preference. 

But, I have a tie-breaker: credit unions have less stringent and often flexible qualification terms for credit. You can’t walk into a bank like Wells Fargo and negotiate the terms of business banking fees, loans, or credit cards. At a credit union, more than not, you can because credit union underwriters usually work in-house and can modify terms and conditions of business and individual financial services. 

So, I say that credit unions are in-fact better than banks. Now, let’s move forward. 

But, Are Credit Unions Better for Business Accounts? 

Best Bank for Small Business

Aside from the general advantages above, there is another aspect of business banking with credit unions worth considering. When you bank with a credit union, you can leverage the perks above when obtaining business credit. For this reason, we prefer to work with credit unions. Alternatively, small community banks can be better for businesses than large banks. 

How to Leverage Business Credit to Transform Your Life 

Now, the Best Credit Unions for Small Business 

You should have a solid understanding of why or why not a credit union might be best for your small business banking. And, here are the top credit unions to join. 

1. Navy Federal Credit Union

With tons of free ATMs sprinkled throughout the United States and several other countries, Navy Federal Credit Union was created for members of the armed forces, DoD, or the National Guard. While you don’t necessarily have to be an active member to join, you must have ties to the military. So, if you are an active member, veteran, or a spouse, parent, grandparent, sibling, child, or grandchild of someone who qualifies, you can qualify for membership. 

If you are not a service member, you will have to apply in-person at a branch location. Once you are approved for a personal account, you can then apply for a business membership. And, Navy Federal has excellent offers for businesses.

  • 3 types of checking accounts (Basic, Plus, & Premium)
  • 3 types of savings accounts (Basic and Jumbo Money Market & Certificate)
  • Real estate, vehicle, and term loans
  • Business lines of credit 

Navy Federal is one of the best credit unions with the lowest rates and fees. Minimum deposits for business savings accounts start as low as $100. And, transaction fees range from $0 to $0.25. And, all accounts earn dividends. 

2. Financial Resources Credit Union

With 13 branch locations in New Jersey and New York, Financial Resources Credit Union has been the top SBA Lender in New Jersey since 2013. So, you know their business financial services are dependable.   

Here’s what you can leverage with Financial Resources Credit Union:

  • 2 types of checking accounts
  • 3 types of savings accounts (Business Purple, Money Market, & Certificates)
  • Real estate, equipment, and term loans
  • Lines of credit 

So, whether you’re investing in real estate or you simply want checking and savings accounts to process your business finances, Financial Resources gives you options. Here, terms are flexible and you can get expedited approval on SBA-backed loans because the institution is a preferred lender. 

3. Sound Credit Union

With 29 locations in the Puget Sound area of Washington State, Sound Credit Union is self-labeled “Washington’s Favorite Credit Union.” And, they stand out from most financial institutions in more than one way. 

For one, they cater to cannabis businesses, which isn’t common. Next, they offer low interest rates, cashback options on certain loans, and they do a lot to support the local community. Furthermore, they have over 5,000 shared branch locations and 30K+ free ATMs nationwide. 

And, businesses can take advantage of the following:

  • Checking accounts
  • Savings and certificate accounts
  • Cannabis (I-502 Analysis) business checking accounts 
  • Business loans
  • Business credit cards 

In addition, with Sound CU, you can access a full suite of business services that includes terminals and point of sale systems, eCommerce payment solutions, mobile card readers, payment acceptance, gift card, reward, and incentive programs, and mobile apps and software. The institution’s tech is as advanced as you can get with most major banks. 

+Honorable Mentions

Obviously, these three credit unions are only a small drop in the ocean of options. So, in case you aren’t able to select one of these three, I want to share four more credit unions that you can research yourself: 

  • Alliant Credit Union – 2 branch locations in Illinois and 80K+ free ATMs
  • Consumer Credit Union – 8 branch locations in Tennessee
  • America First Credit Union – Located in Ogden, Utah
  • Digital Federal Credit Union – 23 branch locations in Massachusets and New Hampshire, 5.9K shared branches, and 80K+ free ATMs 

Why choose a credit union instead of a bank?

Compared to a major bank, a credit union or small local community bank is likely to offer lower fees, increased savings, and more lenient qualification terms for lending. 

What are the disadvantages of credit unions?

Typically, credit unions run operations from their own funds, so they might offer less in the way of mobile apps, online banking features, and other conveniences. But, they still have many valuable perks. 

Are credit unions good for small business?

Credit unions can be beneficial for your small business. They offer lower fees and interest rates, personalized service, a local focus, easier access to credit, and the opportunity for relationship building. Research and compare different credit unions to find the one that suits your specific business needs.

Which bank is best for small businesses?

A small local community bank or credit union can be the best choice for small business banking. Fees are typically lower than those at major banks and lending qualification terms have more wiggle room. These institutions tend to have more control over their terms and conditions.  

How do I choose a bank for my company?

First, create a list of local small community banks and credit unions in your area. Then, call each institution on your list and ask about business checking and savings options as well as underwriting terms for business loans and lines of credit. Finally, choose the option that is the best fit for your operations and goals. 

Final Thoughts

The above-listed credit unions offer the best financial services for businesses. If you want your operations to run smoothly, you can’t go wrong with one of these choices. But, do your homework to make sure you choose the best institution to fit your needs.

To find out which banks and credit unions we’re currently working with to obtain lines of credit up to $100K in as few as 30 days, join Business Credit Workshop today. 

American Express Business Blueprint Review (Formerly Kabbage)

By Joe

American Express Business Blueprint Review

Key Takeaways

  • Kabbage became Amex Business Blueprint, from lending to a full financial platform.
  • Blueprint combines banking, lending, and cash flow insights in one dashboard.
  • Amex Lines of Credit have lower fees than Kabbage (0.95% to 27%, depending on the term).
  • Business Checking offers higher (1.3%) APY, no fees, and a rewards debit card.
  • The iOS app is highly rated, but Android users report issues and bugs.
  • Payment Accept replaced Kabbage Payments, but new customer availability is unclear.
  • The Resource Center provides business insights and financial tools.

Kabbage was once a popular online lender and one of the SBA’s approved PPP loan providers. American Express quietly acquired Kabbage’s platform in 2020, and reworked it to create Business Blueprint—a comprehensive business cashflow dashboard. 

So, what’s changed? And, is American Express Business Blueprint worth checking out? Here, we’ll take a quick peek at why Kabbage might have exited from their operations and learn everything you need to know about the new and expanded offer from Amex. 

This is what’s in store: 

  • What Was Kabbage?
  • What is American Express Business Blueprint?
    • Company Overview
  • How Does American Express Business Blueprint Work?
    • 1. Business Lines of Credit
    • 2. Business Banking Accounts
    • 3 Cashflow Management
    • 4. American Express Business Blueprint App
    • 5. American Express Invoicing & Payments
    • 6. American Express Financial Resources
  • Frequently Asked Questions
  • Final Takeaway

Now, let’s dive in! 

What Was Kabbage? 

What is Kabbage?

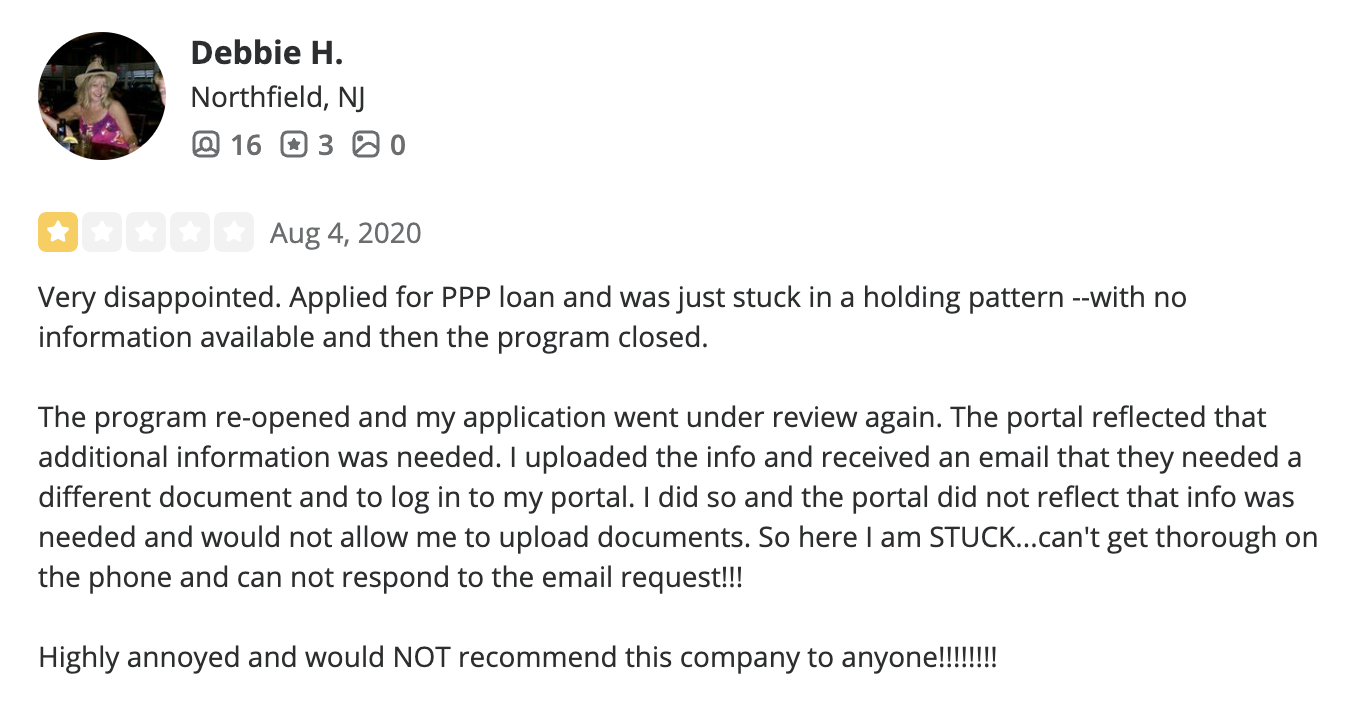
Kabbage, founded in 2009, was an automated lending platform offering quick loans up to $250K for small businesses. Known for convenience but high fees, it paused lending during COVID-19 to focus on PPP loans, earning mostly low ratings. 

Kabbage Reviews

Later, a few years after the purchase by American Express, it transitioned into Amex Business Blueprint, discontinuing its original offer. 

Near the end, Kabbage offered tools like: 

  • Kabbage Checking (competitive APY)
  • Kabbage Payments (low invoicing fees)
  • Kabbage Insights (cash flow tracking)

While useful, these services faced some technical issues before the transition. The hiccups near the end may have made selling the company the wise choice. 

You might also like: No-Doc Business Loans: Get Funds Without Proof of Income 

What is American Express Business Blueprint? 

American Express Business Blueprint

When I first heard that Amex had acquired Kabbage (whose lending funds used to come from Celtic Bank), I said, “If the brand does bring back working capital in the future, it will most likely come directly from Amex itself. We’ll just have to wait around to see.”  

Well, that future is now. 

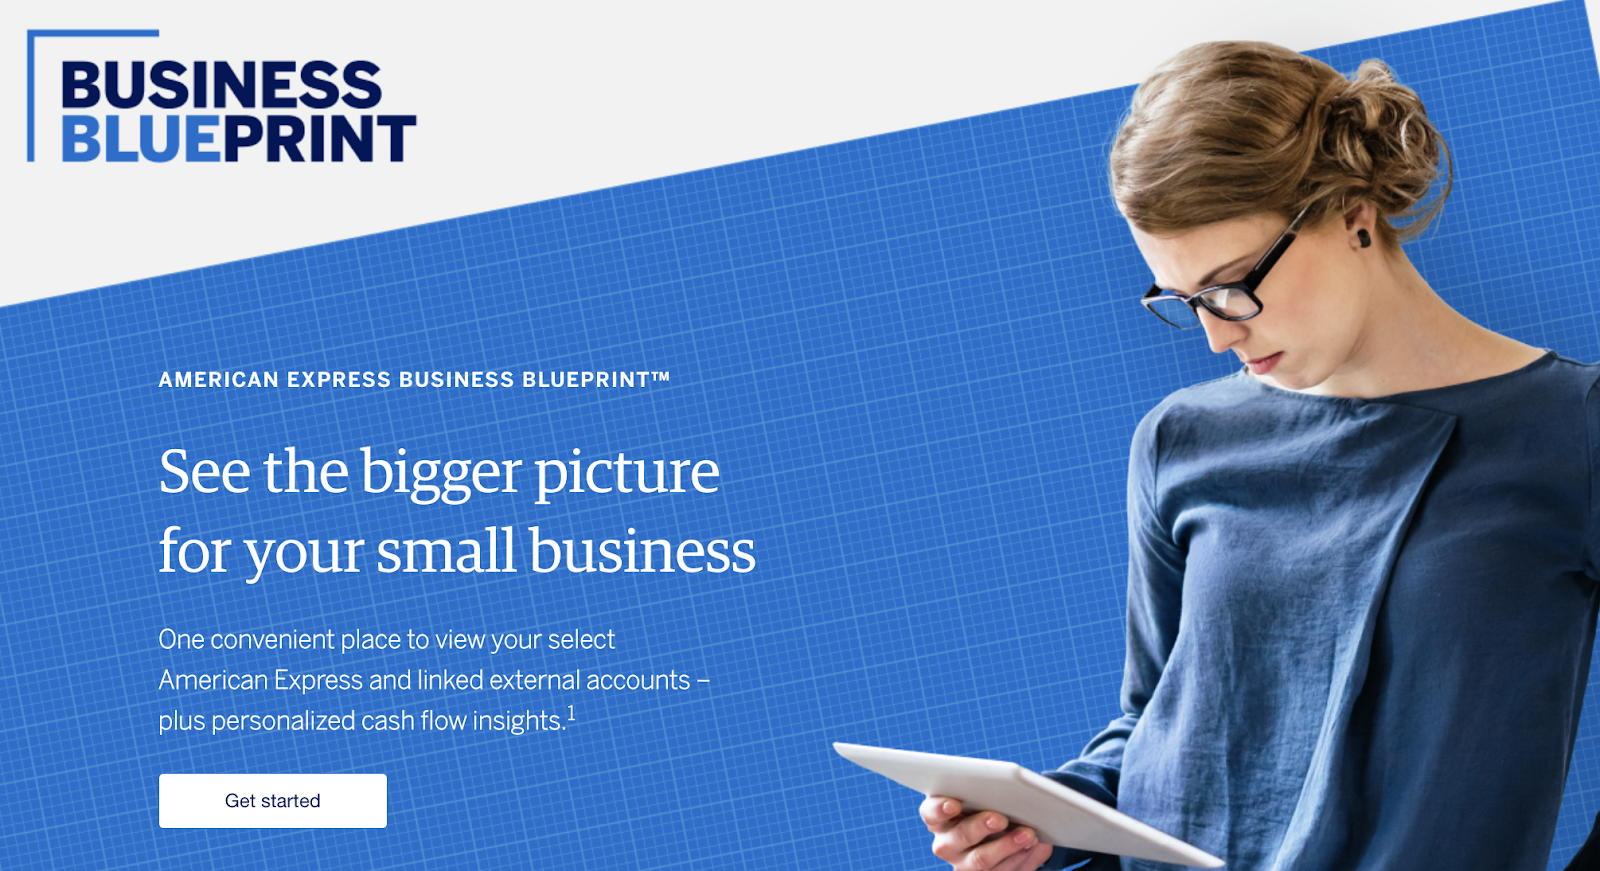
American Express Business Blueprint is a free platform positioned to help small businesses manage their cash flow. It lets you view your American Express business products and linked external accounts in one place. Then, it provides personalized insights to help you make informed financial decisions. 

With the tool, you can access features like a 30-day bank account balance projection, which uses data from your linked accounts to help you anticipate future balances. In a nutshell, business Blueprint aims to simplify financial management for small business owners.

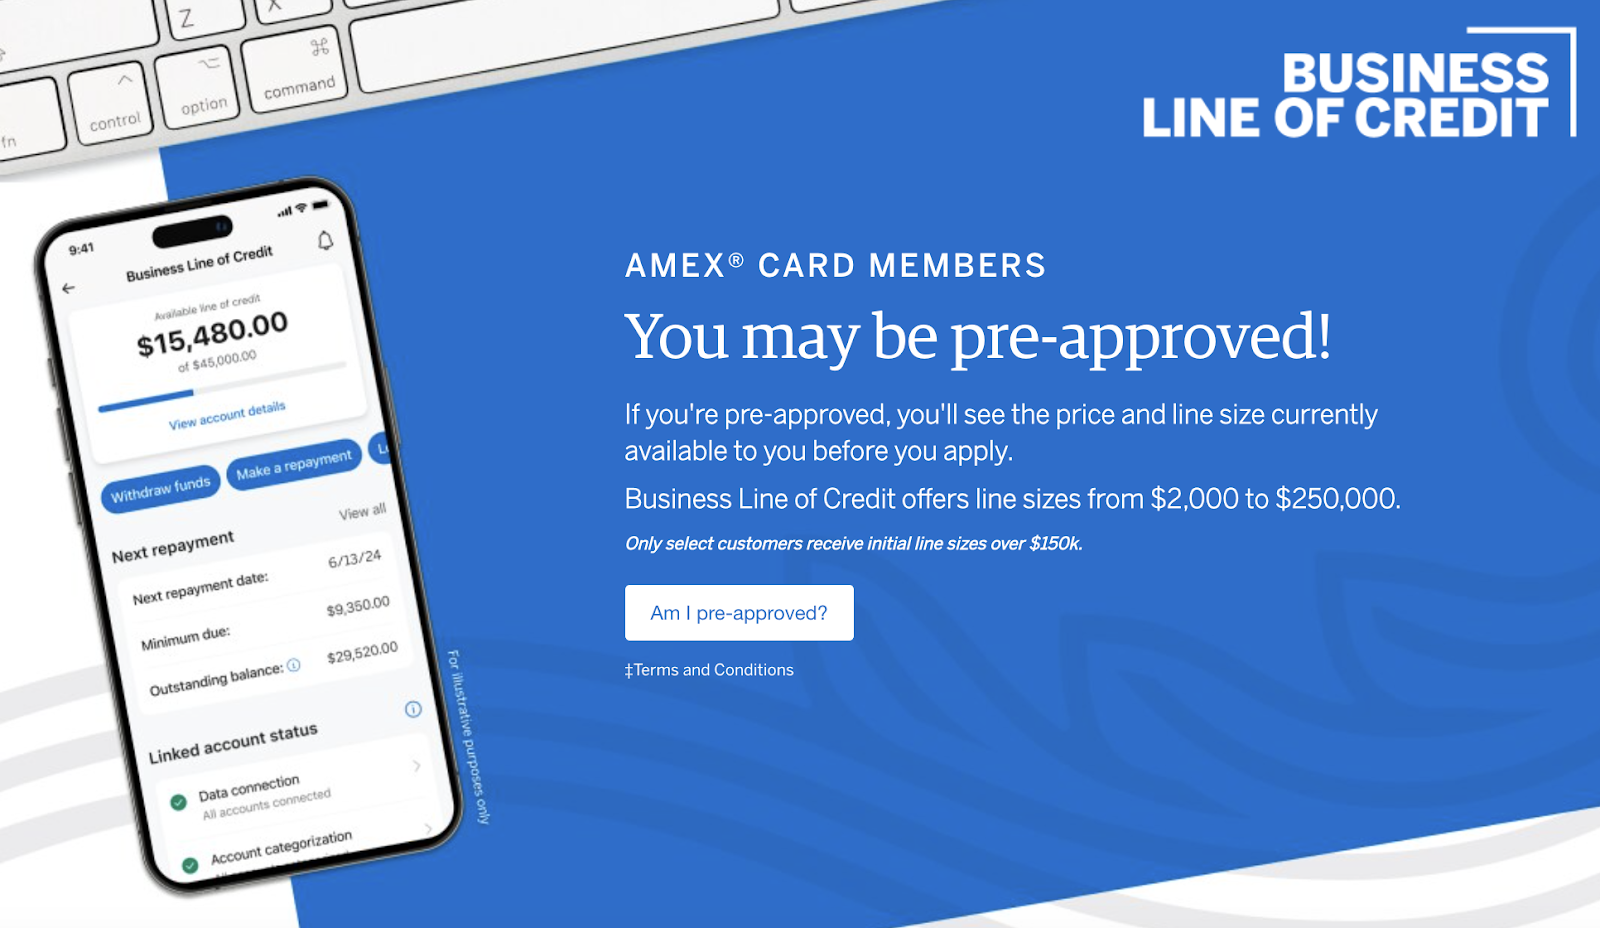
Moreover, Amex is offering a Business Line of Credit up to $250K (same as Kabbage), with no mention of Celtic Bank. Today, these loans are serviced directly by American Express National Bank.  

Recommended: Amex Business Checking Review: What You Need to Know…Really 

Company Overview

American Express Business Blueprint Benefits

American Express, aka Amex, is a global financial services company with roots dating back to 1850. Founded by Henry Wells, John Butterfield, and William Fargo—names you might recognize from Wells Fargo—Amex has built a reputation for reliability and innovation in finance. 

Initially known for credit cards, charge cards, and traveler’s checks, the company has since expanded its offerings to include business checking accounts (and, now working capital) further solidifying its leading position in the financial world.

Headquartered in New York and led by CEO Stephen Squeri, Amex stands out as a trusted name in American finance. It’s publicly traded and has endured as a stable force in a fast-evolving industry. 

You might also like: A Complete, Unfiltered Amex Business Gold Card Review 

How Does American Express Business Blueprint Work? 

American Express Business Blueprint login

As I said before, American Express Business Blueprint is free. And, you can log in with existing credentials, if you’re already an American Express member, or create an account. 

Once you’re in, you’ll have access to a lot of the same features and services that were available with Kabbage, but with some notable improvements. 

1. Business Lines of Credit

american express business line of credit

Kabbage’s fixed-rate loan fees were steep, ranging from 24-99% APR, with no savings for early repayment, no long-term options, and approval limited to businesses with online checking or PayPal. 

In contrast, Amex Business Lines of Credit offer a more affordable alternative, with funding from $2K to $250K secured by business assets and personal guarantees. 

Amex’s fees range from:  

  • 0.95% to 6.05% for single repayment loans (1 to 3 months)
  • 3% to 27% for installment loans (6 to 24 months)

So, Amex offers a much less expensive business lending option than Kabbage was able to. They also offer reduced costs with early repayment on installment plans. However, you must be an Amex cardholder to apply.

2. Business Banking Accounts

American Express Business Checking

Before the transition, there was no such thing as a Kabbage business savings account. Likewise, there is no American Express business savings account (though they do have a consumer savings option). 

Kabbage Checking offered FDIC-insured banking with 1.10% APY earned on funds, which they declared was the best deal you’ll find. This wasn’t true with 2% earnings from Bluevine and varying larger amounts from several credit unions. 

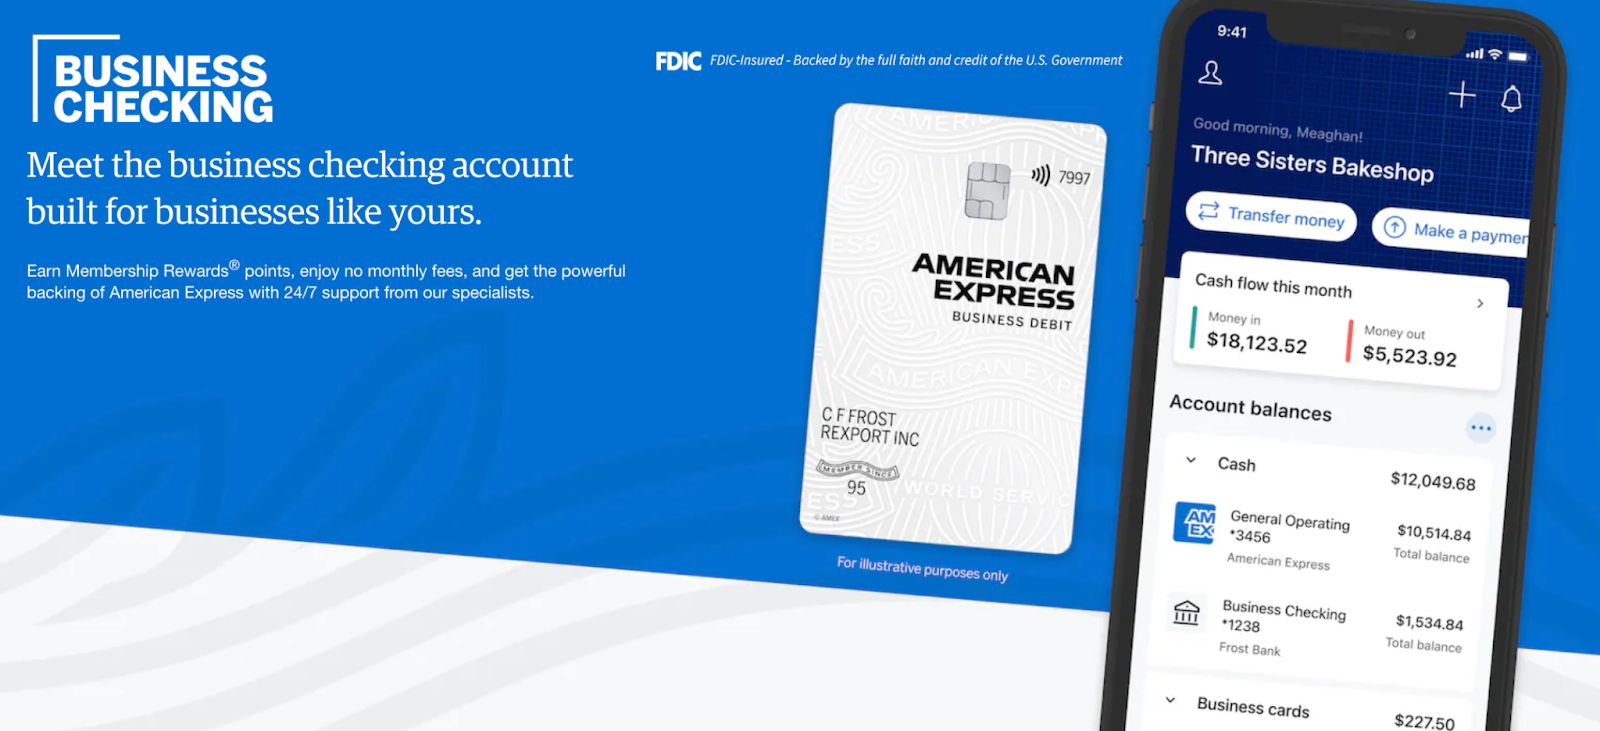
Today, American Express Business Checking is worth taking a look at.  Their business checking account earns 1.3% APY on balances up to $500K and charges no  monthly maintenance fee—They also offer a rewards debit card that earns 1 point with every $2 spent, and their high deposit limits can house balances up to $5 million. 

However, they lack integrations for tools like QuickBooks and don’t accommodate cash deposits (despite free MoneyPass™ ATM access). Currently, they don’t offer virtual cards, either. 

Recommended: Best Business Bank Accounts: 5 Top Picks for Small Businesses   

3. American Express Business Blueprint Cashflow Management 

Amex Cashflow Management

Kabbage Insights, in my opinion, was comparable to Quickbooks. While it did deliver visual reports, it was basically an accounting platform. Theoretically, it allowed users to view all their accounts in one place for a clearer picture of cash flow and revenue. 

Users could link the system to various banks, including smaller credit unions. PayPal and Stripe integrations were unavailable when I reviewed Kabbage, despite being advertised. 

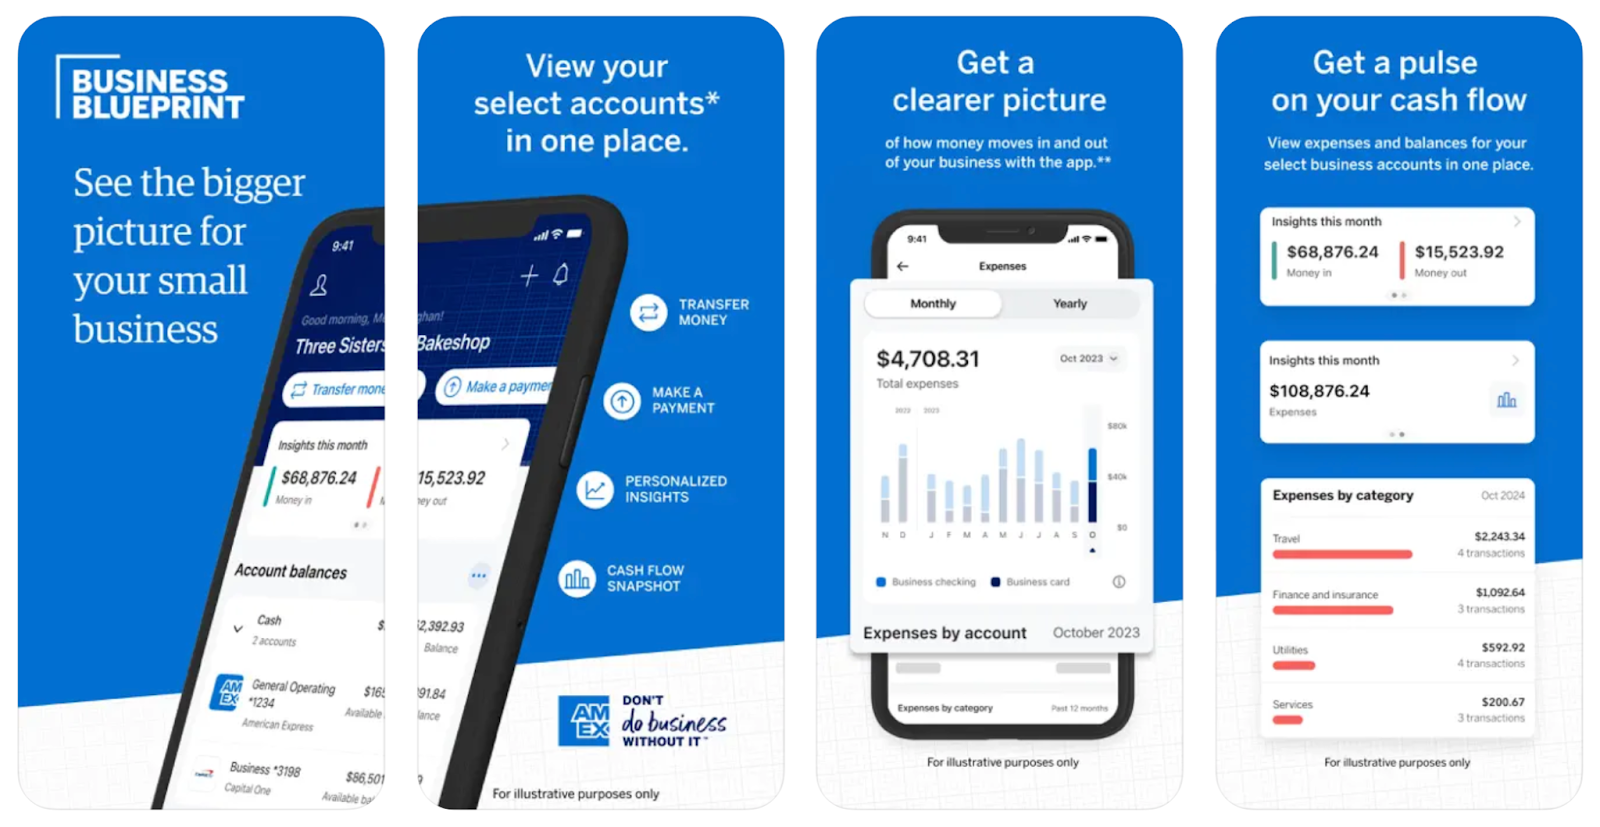
Today, Business Blueprint™ is the core of Amex’s small business offer, with a real-time financial dashboard that consolidates Amex business products and linked external accounts. 

It offers: 

  • Personalized cash flow insights
  • Business  income and expense tracking
  • 30-day balance projections
  • A bird’s-eye view of your financial health

You can get all of this in one place. It’s designed to help you focus on growth instead of spreadsheets. The platform is free, but individual Amex financial products have their own fees and eligibility requirements.

You might also like: Plastiq Review: Can Plastiq Really Simplify Your Finances? 

4. American Express Business Blueprint App 

American Express Business Blueprint App

Back in September 2020, I noted that Kabbage’s web app and mobile app both seemed a little wonky. I assumed this was because they had recently furloughed staff and cut back on their service offer for the time being. 

Today, the American Express Business Blueprint app, available on both iOS and Google Play marketplaces, seems upgraded. 

Apple users give The Amex Business Blueprint™ app a 4.8 out of 5 rating, based on 8,500 reviews. Users appreciate its convenience and ease of use. However, some have reported limitations in banking functionalities, like viewing canceled checks and scheduling payments. 

However, most Android users seem find the Amex Business Blueprint app frustrating due to: 

  • Persistent login issues
  • Slow transfers
  • Frequent glitches
  • Poor support

Many of them prefer using the web instead.

You might also like: What is the Best Personal Finance Software? Free and Paid Options 

5. American Express Invoicing & Payments 

American Express Business Blueprint Payments

Kabbage Payments was an online invoicing platform with competitive rates at 2.9% + $0.25 per transaction, slightly lower than most major competitors. It supported email and web link billing, with next-day deposits for transactions processed before 5 PM. 

Users could also create a unique URL to sell gift certificates ranging from $15 to $500. 

Today, American Express Payment Accept is a service designed to help small businesses process card payments online efficiently. It offers a straightforward solution with transparent pricing, aiming to make payment processing simple and quick.

*But, they may not be accepting new customer applications at this time—Check with Amex for Updated info. 

You might also like: Melio Payments Review: Can It Make Business Payments and Getting Paid Easier? 

6. American Express Financial Resources 

American Express Business Blueprint Customer Service

Kabbage’s “Resource Center” was a blog dedicated to financial advice for business owners. I found the articles to be pretty useful, easy-to-understand, and worth a look. 

Kabbage Funding Reviews

American Express, on the other hand, has a full suite of resources for small business owners through its Business Blueprint™ platform. 

This includes a Resource Center featuring: 

  • Articles on various small business topics
  • Customer success stories
  • A massive help center 

It provides not just articles but also tools, customer success stories, and guided resources to help business owners manage and grow their finances more effectively.

You might also like: 41 Companies That Help Build Business Credit [Beyond Net 30 Vendors] 

Frequently Asked Questions

Is it hard to get an American Express business line of credit?

Approval for an Amex business line of credit depends on factors like your business’s financial health, credit score, and cash flow. While the process isn’t overly difficult for well-qualified applicants, Amex does require a personal guarantee and evaluates your business assets carefully.

Does Amex business report to Dun & Bradstreet?

Yes, American Express reports business credit activity to Dun & Bradstreet as well as other major credit bureaus, helping you build your business credit profile.

Why do so many businesses refuse Amex?

Some businesses avoid accepting Amex due to higher transaction fees compared to other credit card providers. These fees can cut into profit margins, especially for small businesses.

Is American Express business hard to get?

Obtaining an Amex business card or account generally requires a good to excellent credit score and stable business finances. While not excessively hard, it may be challenging for newer businesses or those with weaker credit profiles.

What is the minimum income for Amex Business Platinum?

American Express doesn’t specify a minimum income requirement for the Business Platinum Card. But, MyFico forums have a lot of anecdotal stories that suggest that they expect applicants to demonstrate significant income or business revenue to justify approval.

Final Takeaway

American Express Business Blueprint took what Kabbage started and expanded it into a full-scale financial platform. With better lending terms, a solid business checking account, and improved cash flow tools, it’s a clear upgrade. 

However, some drawbacks remain, like limited integrations and an inconsistent mobile app experience. If you’re an Amex cardholder looking for streamlined business banking and financing, it’s worth considering—just be aware of its gaps.

Are you ready to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today!

FairFigure Review: Is it Really That Easy to Build Business Credit?

By Joe

FairFigure review

I first discovered FairFigure when writing up my most recent post, a comprehensive Fidextech review. I found it so interesting that I put it at the top of the list to research next. Now, here’s everything I know. 

Let’s take a look at what FairFigure is, see an overview of company leadership, and explore the features of the card in detail. 

This is what’s in store: 

  • What is FairFigure?
    • Company Overview
  • FairFigure Capital Card Features
    • 1. No Personal Guarantee
    • 2. Adjustable Spending Limits
    • 3. Net 30 or Net 60 Repayment Terms
    • 4. Personal and Business Credit Monitoring
    • 5. Identity Theft Protection
    • 6. Reporting to Business Credit Bureaus
  • FairFigure Partnership Opportunity
  • Conclusion: Is FairFigure Legit?

Now, let’s roll! 

What is FairFigure?

Fair figure net 30

FairFigure is a platform designed to help small business owners build, monitor, and improve your business credit. They offer a service that allows you to track both your business and consumer credit scores in real time. It includes features like a Business Credit Correct tool that helps identify and fix incorrect information. 

FairFigure also offers the FairFigure Business Capital Card, which you can use to get funding without personal credit checks or personal guarantees.

Key features include:

  • Business and consumer credit monitoring.
  • FairFigure Capital Card that helps build credit while providing same-day funding.
  • Payment reporting to commercial credit bureaus. 
  • Identity Theft Protection and Darknet Scanner to help secure your company.

With FairFigure, there are no personal credit checks for funding or credit applications, since they rely on business EINs instead. The company positions itself as a tool to help businesses grow by helping them improve credit scores and secure better funding options.

You might also like: Low-Risk NAICS Codes +Best SIC Codes for Business Credit in 2024 

Company Overview

Is Fair Figure legit?

FairFigure Capital LLC is a Fort Lauderdale-based company that was founded in 2021 by Dana Angelino. Angelino happens to own and co-own several other companies, including numerous net 30 offers that help people build business credit. 

His other businesses include: 

  • Crown Office Supplies
  • Shirtsy
  • Signsy
  • Greentees
  • Coconut Bikinis
  • A few others

So, FairFigure’s founder is as informed as anyone could be about the business credit building market and net 30 offers. Other than a bank executive, I can’t think of a better background for a business credit builder company leader. 

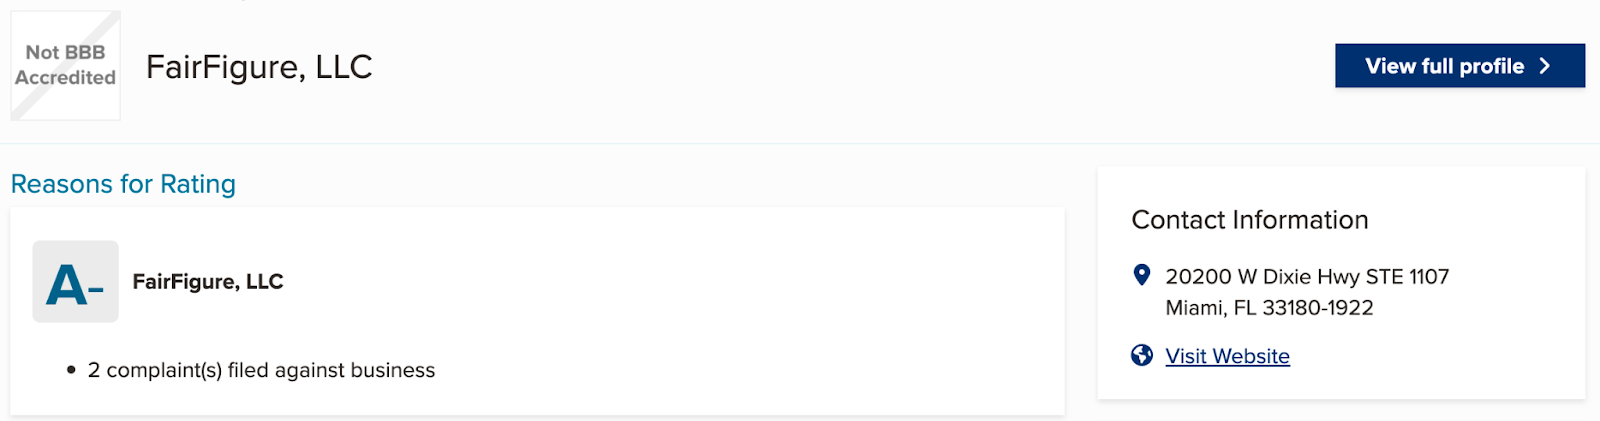
While FairFigure is not Better Business Bureau-accredited, they have an A- rating on the platform, with minimal complaints and a handful of positive reviews from satisfied users. 

FairFigure reviews complaints

I didn’t find any FairFigure reviews on Trustpilot, mentions on Reddit, or staff reviews on Glassdoor. Most of the reviews I did find appeared to be affiliate reviews, so I assume they were somewhat biased. 

FairFigure credit card reviews

Without ever having applied for the card myself, I can only say that, if I were a betting man, I would wager that the company is trustworthy based on what I know about its leadership. 

With that said, I did notice something about the offer that is quite misleading. FairFigure claims to offer cashback on card purchases. 

FairFigure coupon

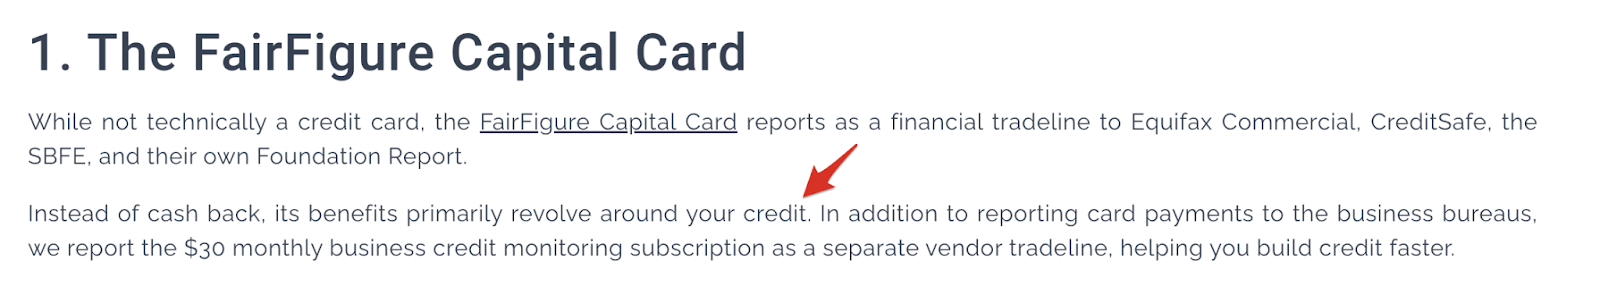
However, while I was searching for the cashback amount, I came across a blog post on the official website that states: “Instead of cash back, [the FairFigure Capital Card] benefits primarily revolve around your credit.”

FairFigure does not offer cashback

I’m not a fan of deceptive messaging or brands with a lack of transparency, so this doesn’t sit so well with me. But, even without cashback, the offer is worth taking a look at. 

You might also like: 41 Companies That Help Build Business Credit [Beyond Net 30 Vendors] 

FairFigure Capital Card Features

FairFigure business credit card

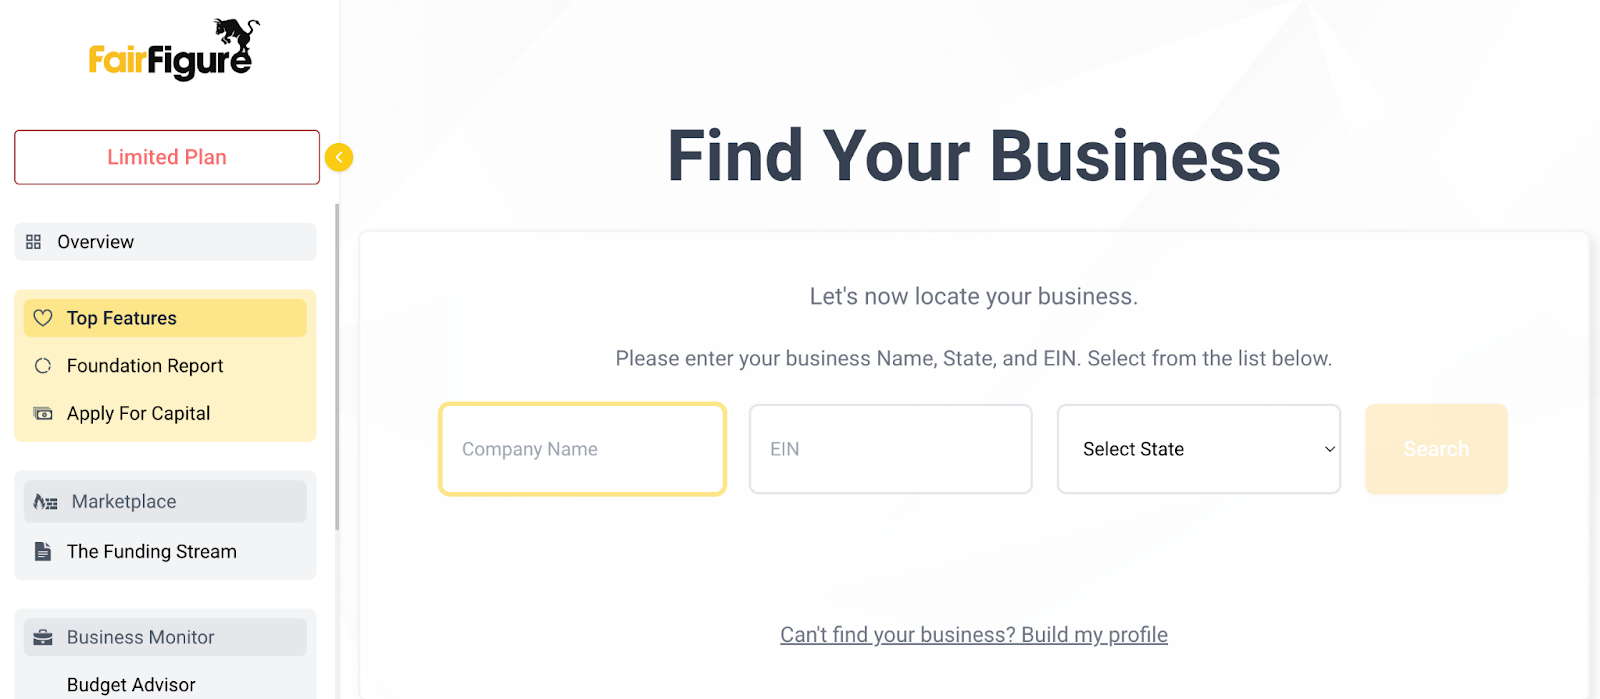
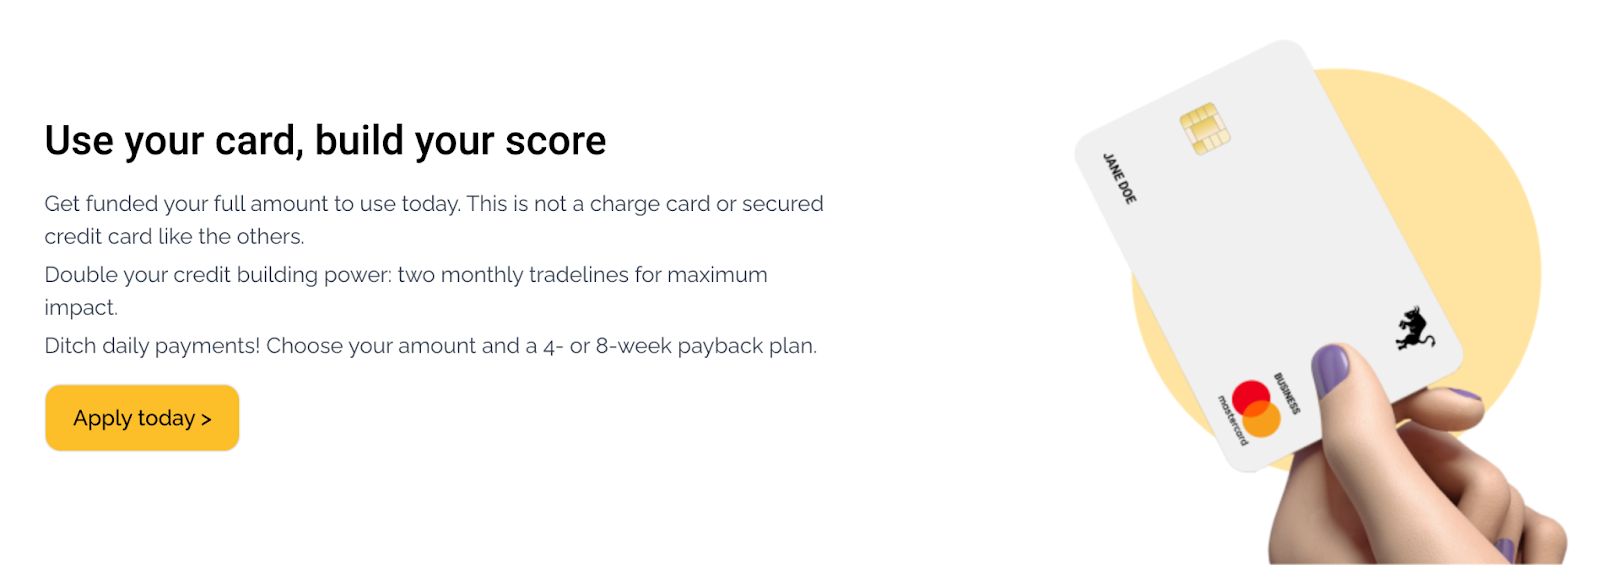
The FairFigure Capital Card is a “no PG” (no personal guarantee) business credit builder card. It lets you apply using your company’s EIN, which allows you to build business credit without personal credit checks or guarantees. 

The card offers: 

  • Flexible four or eight week repayment terms. 
  • Credit monitoring tools. 
  • Identity theft protection.
  • Reporting to commercial credit bureaus. 

Moreover, it provides funding based on business revenue and reports payments to key business credit bureaus, which helps boost your credit score. Ultimately, it’s designed to separate personal and business finances, which makes it practical for small businesses that want to build credit and access funding.

Note, funds must be repaid in full within the payback terms you choose—It’s more like a corporate card, not a credit card. 

Recommended: Business Credit Cards You Can Get Without a Personal Guarantee 

1. No Personal Guarantee

Fairfigure login

You don’t have to worry about personal credit checks or guarantees when you apply for the FairFigure Card—This keeps your personal and business finances separate, which reduces the risk to your personal credit score and assets. 

No PG business credit offers are perfect for businesses that want to build credit solely through their EIN.

You might also like: Here’s How to [Actually] Get Business Credit With Just an EIN +More Options 

2. Adjustable Spending Limits

Fairfigure credit limit

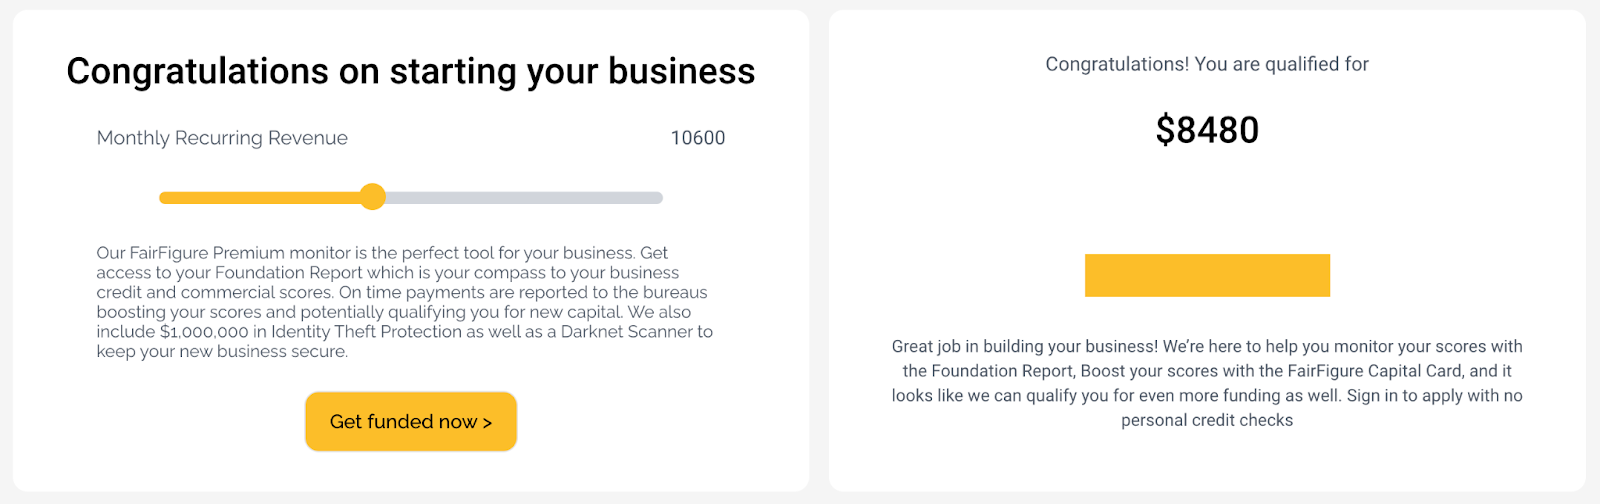
Your spending limit with FairFigure is based on your business revenue. For example, if your business meets the qualifications, you could start with a $1,000 limit. As your revenue grows, so does your spending power. 

So, if your business brings in $10K in monthly revenue, you might qualify for an $8K limit. The scalability allows you to extent your purchasing power as your business expands and gives you access to more capital when needed.

3. Net 30 or Net 60 Repayment Terms

Business credit for new business

Net 30 or net 60 terms refer to how much time you have to pay back what you’ve borrowed. With FairFigure’s card, you can choose either 30 or 60 days to pay your balance in full. 

If you choose net 30, you’ll need to pay off your card in full within 30 days of making a purchase. And, if you choose net 60, you have 60 days. 

4. Personal and Business Credit Monitoring 

Business credit builder

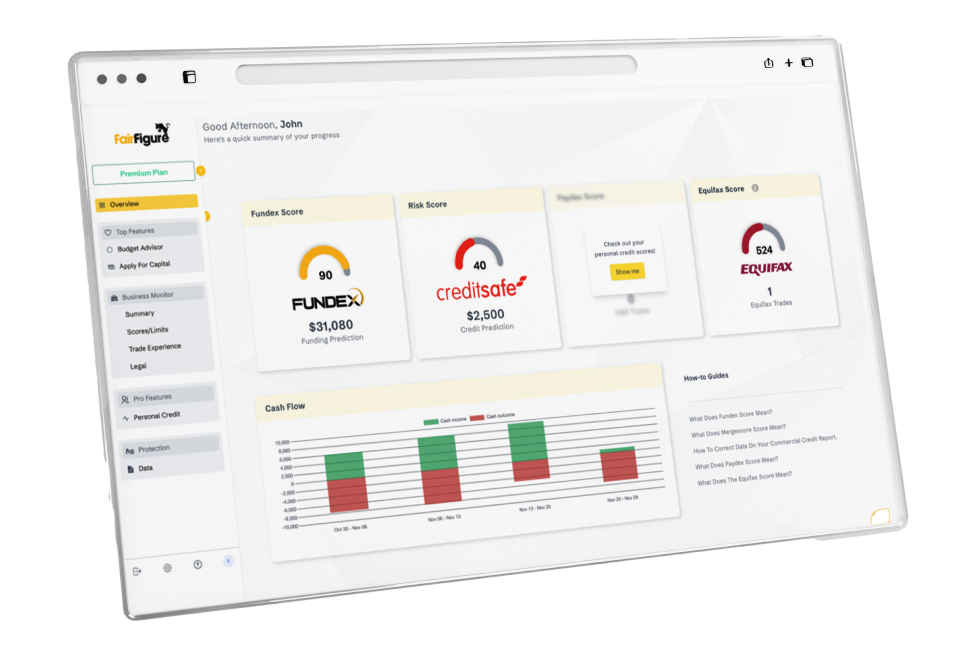
For $30 per month, FairFigure offers business credit monitoring that helps you track your financial health. 

FairFigure monitors business credit scores from: 

  1. Fundex
  2. CreditSafe
  3. Equifax

And, provides consumer credit monitoring from: 

  1. Equifax
  2. Transunion
  3. Experian

This service not only keeps you updated on your credit scores but also reports your $30 monthly subscription as a separate vendor tradeline. 

So, paying for the monitoring service helps build your credit faster by adding an extra positive payment to your business credit report.

5. Identity Theft Protection

Business credit cards for fair credit

With the $30 credit monitoring subscription, FairFigure includes $1 million in identity theft protection to safeguard your business. You’ll also benefit from a Darknet scanner that alerts you if your business’s sensitive information is exposed. 

With this added security, you can focus on growing your business without the worry of identity theft.

Recommended: 14 Best Credit Monitoring Services for Scores, Reports, & ID Theft Protection 

6. Reporting to Business Credit Bureaus

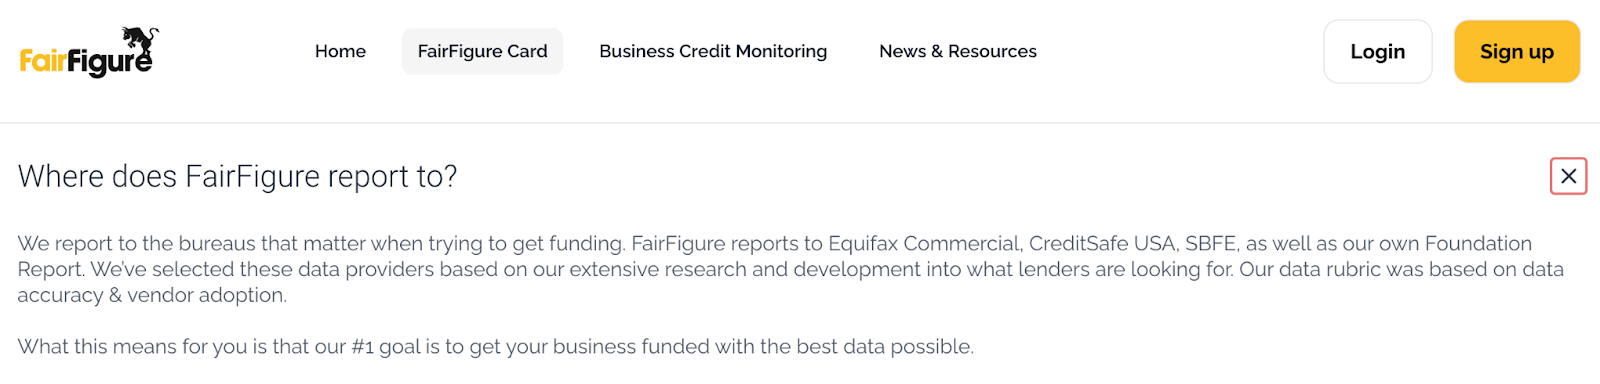
Who does Fair Figure report to?

According to FairFigure’s official website, they report data to: 

  1. Equifax Commercial
  2. CreditSafe USA
  3. SBFE
  4. Their own Foundation Report

So, you can get your credit monitoring and FairFigure card payments reported to these bureaus. 

However, there is no current indication that FairFigure reports to Experian Business or Dun & Bradstreet. This may change, so it’s a good idea to check their official website for the most up-to-date information.

You might also like: Everything You Need to Know About a DUNS Number – and Why You Should Care 

FairFigure Partnership Opportunity

FairFigure waitlist

Again, I first learned about FairFigure through Fidextech, a web design and marketing agency that offers FairFigure net 30 terms to their clients, which caught my attention. 

Through the affiliate program, you can earn up to $120 for each client or customer who signs up and is approved for the FairFigure Capital card. The card allows you to offer net 30 terms to your clients who can then pay you while building positive payment histories. 

The program supports new businesses by establishing their profiles with credit bureaus and helps most business owners get approved for at least $1,000 in initial funding. 

You might also like: A Complete Fundwise Capital Review: Should You Use Their Business Funding Services? 

Conclusion: Is FairFigure Legit? 

So, can you really build business credit that easily with FairFigure? It’s a bit more complex than a simple yes or no. While FairFigure offers two tradelines—the Capital Card and the monitoring service—these alone may not be enough to significantly boost your business credit. 

Still, you can use the FairFigure card to pay your other tradelines, which might be super helpful. Keep in mind that paying $30 for credit monitoring is optional and may not be necessary on the business credit building journey; there are other ways to track your credit without this added expense. 

Ultimately, FairFigure provides some solid tools, but building substantial business credit often requires more than just these offerings. Consider your options carefully before you dive in.

Want to learn how to obtain up to $100K in business credit in as few as 30 days? Join Business Credit Workshop today!

Space Coast Credit Union Review: SCCU’s Small Business Offer

By Joe

Space Coast Credit Union

Here, I want to introduce Space Coast Credit Union (SCCU) and point out some of the special advantages that credit unions offer compared to large banks, particularly for businesses. You’ll find an overview of SCCU’s business credit cards, loans, and other small business financial products.

 And, you’ll see insightful comparisons of some of SCCU’s accounts with highlights of their benefits, features, and how they cater to your needs. By the end, you’ll have a clear idea of what SCCU has to offer and whether or not you should consider them for your business banking. 

This is what’s in store: 

  • What is Space Coast Credit Union?
    • Locations Served
    • Membership and Eligibility
  • Business Financial Products and Services
    • 1. Business Banking/Checking
    • 2. Business Credit Cards
    • 3. Business Loans
    • 4. Business Savings & Investment Opportunities
    • 5. Treasury Services
    • 6. Mobile App
  • SCCU Customer Service
  • SCCU Community Involvement
  • Frequently Asked Questions
  • Conclusion

Now, let’s get ready for takeoff!

What is Space Coast Credit Union?

Space Coast Credit Union Review

SCCU is a financial institution that offers a range of services tailored for both personal and small business needs. Founded in 1951, it has grown to become one of the largest credit unions in Florida, serving over 500K members.

The credit union was established with the mission to give members competitive financial products and services and maintain a strong commitment to the community. Over the years, SCCU has expanded its offerings to include comprehensive banking solutions for individuals and businesses.

SCCU helps small businesses through a variety of offers:

  • Business banking
  • Business loans
  • Business credit cards
  • Merchant services

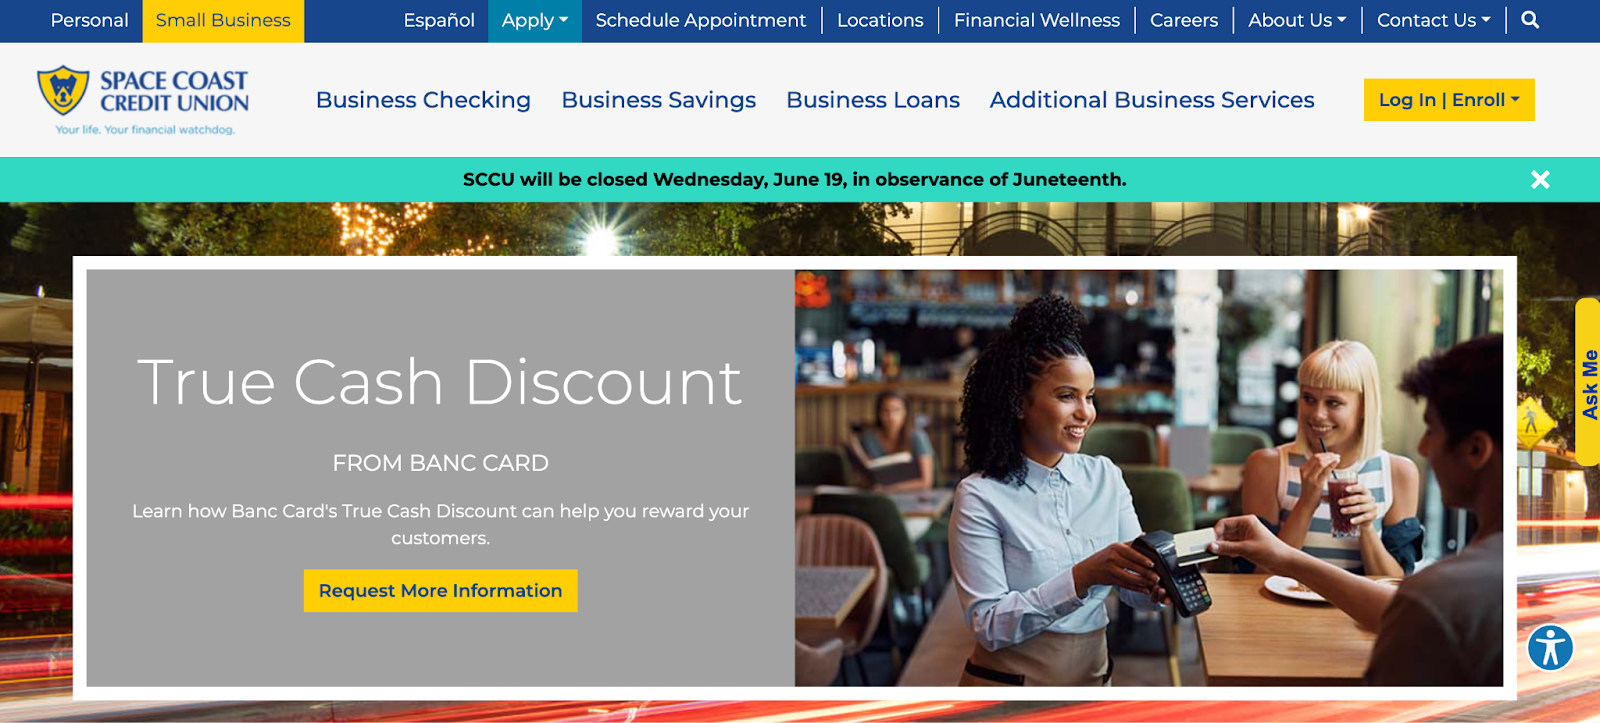
SCCU offers some unique benefits including the “True Cash Discount” from Banc Card, which promotes cash transactions and reduces fees. Plus, SCCU’s Business Advisors provide personalized guidance on strategic planning and financial management. 

Space Coast Credit Union Reddit

Finally, their “Honestly Free Business Checking” really has no hidden fees and no required minimum balance. 

Recommended: 3 Best Credit Unions for Small Business Banking in 2024 

Locations Served

Space Coast Credit Union near me

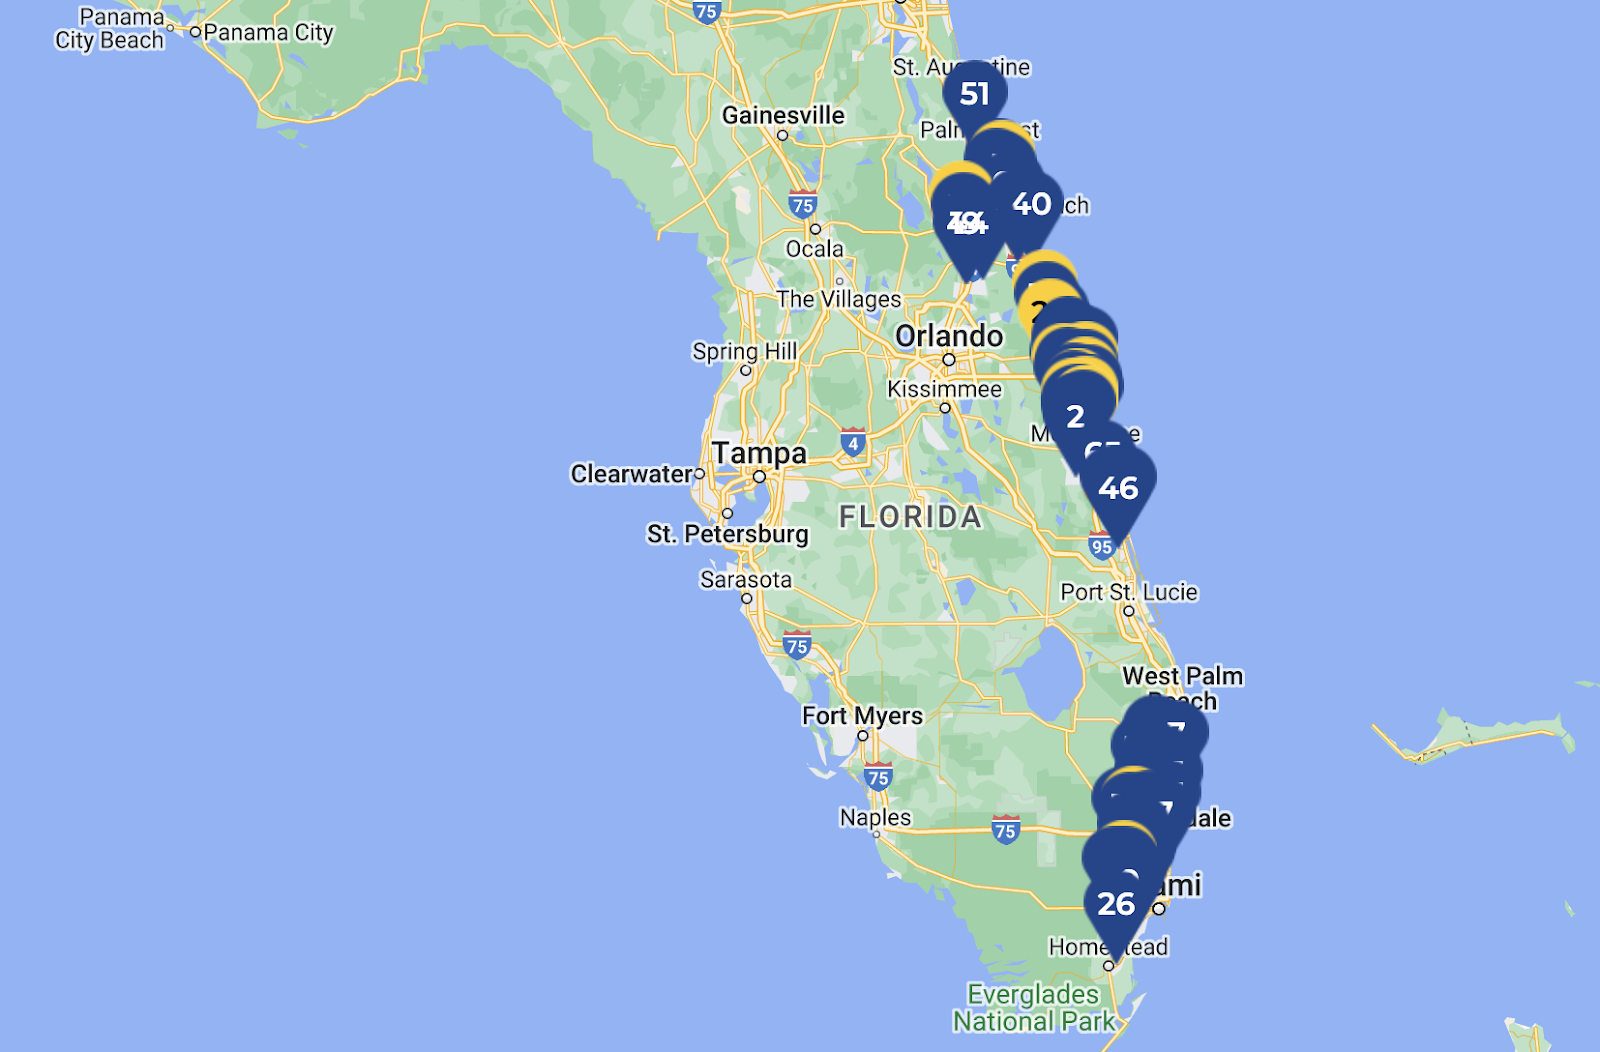
SCCU operates in the eastern part of Florida, with a strong presence in Miami, Melbourne, Palm Bay, Boca Raton, and Fort Lauderdale. They have approximately 60 branches spread across these areas to make sure members have convenient access to banking services. 

Branches are equipped with features like ATMs with night drop boxes, drive-thrus, safe deposit boxes, coin sorters, and some offer specialized services like deposit ATMs and extended hours—Their online banking services further extend accessibility to members nationwide.

You might also like: Is BHG Financial Legit? Personal & Business Loans, VC, & More 

Membership and Eligibility

Space Coast Credit Union login

To become a member of SCCU, you need to reside in one of the 34 counties in Florida that SCCU serves. These counties include Alachua, Brevard, Broward, Charlotte, Citrus, Clay, Collier, Duval, Flagler, Hernando, Hillsborough, Indian River, Lake, Lee, Manatee, Marion, Martin, Miami-Dade, Monroe, Nassau, Okeechobee, Orange, Osceola, Palm Beach, Pasco, Pinellas, Polk, Putnam, Sarasota, Seminole, St. Johns, St. Lucie, Sumter, and Volusia.

If you meet this criteria, you can join SCCU by opening a personal Share Savings Account online or at any of their 65 branch locations. Your Share Savings Account not only makes you a member but also a co-owner of the credit union—It comes with benefits like earning dividends on the first dollar of savings and no monthly maintenance fees.

When you join, SCCU will check your account, credit, and employment history to verify your eligibility. This may include getting reports from third parties, including credit reporting agencies. Once your membership is established, you can access SCCU’s business products and services.

To open a business account online or in-person with SCCU, you’ll need to provide:

  • Business legal name
  • Ownership percentage (and have at least 25% ownership
  • Employer Identification Number (EIN)
  • Articles of Organization, partnership registration, or fictitious name verification from Sunbiz
  • Partnership agreement (if applicable)
  • Signers/Beneficial owner information

SCCU will provide a Resolution of Authority Form and a Business Service Account Agreement. 

You might also like: Novo Bank Review: First-Rate Small Business Banking or Scam? 

Business Financial Products and Services

Whether you’re starting a new venture or expanding an existing one, SCCU offers many tools to help your business thrive. Learn more about their business banking, loans, lines of credit, and merchant services.

1. Business Banking/Checking

SCCU business checking

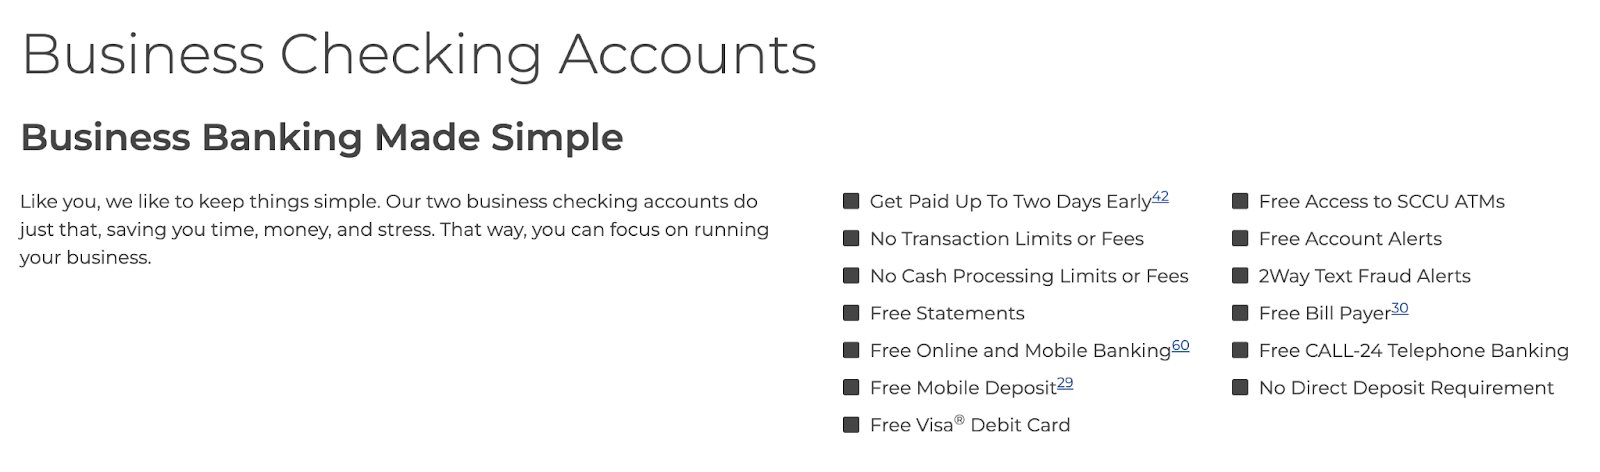
SCCU offers two main business checking accounts: Free Business Checking and Business Interest Checking. These accounts are designed to save you time, money, and stress, so you can focus on running your business.

  1. Free Business Checking is SCCU’s most popular option. It comes with no direct deposit requirement, no minimum balance requirements, no transaction limits or fees, and no monthly low balance fee. You only need a minimum opening deposit of $50. This account is ideal if you want a straightforward, cost-effective way to manage your business finances without additional costs.
  2. Business Interest Checking provides the added benefit of earning interest on your account balance, without the need for traditional bank sweeps. Like the Free Business Checking account, it also has no direct deposit requirement and no minimum balance requirement—This account allows your money to work for you while maintaining the simplicity of no monthly fees and transaction limits.
Free Business CheckingBusiness Interest Checking
Minimum Opening Deposit$50$50
Monthly Low Balance FeeNoneNone
Minimum Daily BalanceNoneNone
Transaction FeesNoneNone
StatementsFreeFree
Multiple Business Account HoldersAllowedAllowed
Earns InterestNoYes

Both accounts offer numerous free services, including:

  • Free statements
  • Free online and mobile banking
  • Free mobile deposit
  • Free Visa® debit card
  • Free access to SCCU ATMs
  • Free account alerts and 2-way text fraud alerts
  • Free bill payer
  • Free CALL-24 telephone banking
  • No processing limits

Plus, SCCU advertises that you can get paid up to two days early. 

2. Business Credit Cards

SCCU business credit card

SCCU offers a Visa® Platinum Business Credit Card with rewards and competitive interest rates. You earn 3 points per dollar at restaurants and office supply stores, 2 points per dollar on gas, and 1 point per dollar on all other purchases. 

Points can be redeemed for: 

  • Cash back
  • Gift cards
  • Travel
  • Entertainment
  • Theme park tickets

The card features a 0.00% introductory APR for the first 6 billing cycles on purchases, balance transfers, and cash advances. After the intro period, the APR is based on creditworthiness, with rates as low as Prime Rate (8.5% as of today) + 7.99%. 

With this card, there are no annual fees, balance transfer fees, or cash advance fees. But, you can incur a late payment fee of up to $27 and there’s a minimum finance charge of $0.50.

Unique perks for cardholders include: 

  • Free 2-way text fraud alerts
  • Visa zero liability protection
  • Digital wallet payment options
  • Contactless payments
  • Card controls through the mobile app 

The Visa® Platinum Business Credit Card provides financial flexibility, rewards, and essential security features.

Recommended: Corporate vs Business Credit Card: What’s the Difference? 

3. Business Loans 

SCCU business loans

SCCU offers a handful of business loans:

  • Commercial real estate loans
  • Commercial construction loans
  • Commercial vehicle loans
  • Business equipment loans

Commercial real estate & construction loans help you build, buy, or refinance properties like offices, warehouses, or retail spaces. SCCU provides loans for owner-occupied and investor-owned properties, as well as commercial construction. There are no application fees or pre-payment penalties, and terms vary based on the project. 

For construction loans, you can expect a structured draw schedule tied to construction milestones.

Commercial vehicle & business equipment loans are ideal for purchasing or refinancing business vehicles or equipment—They offer low credit union rates and flexible terms. Like real estate loans, there are no application fees or pre-payment penalties. Terms range from 24 months to 10 years or more, depending on the equipment and the lender.

For commercial vehicles and equipment loans, the benefits include separating personal and business finances, potential tax deductions, and full ownership of the vehicle or equipment.

SCCU offers fixed- and variable-rate loans, with specific rates based on creditworthiness and loan type. While they don’t disclose their c